
Battery Swapping Policy Explained: What It Means for EV Loan Risk
- Published on Sep 10, 2026
- Read Time 7 mins
-
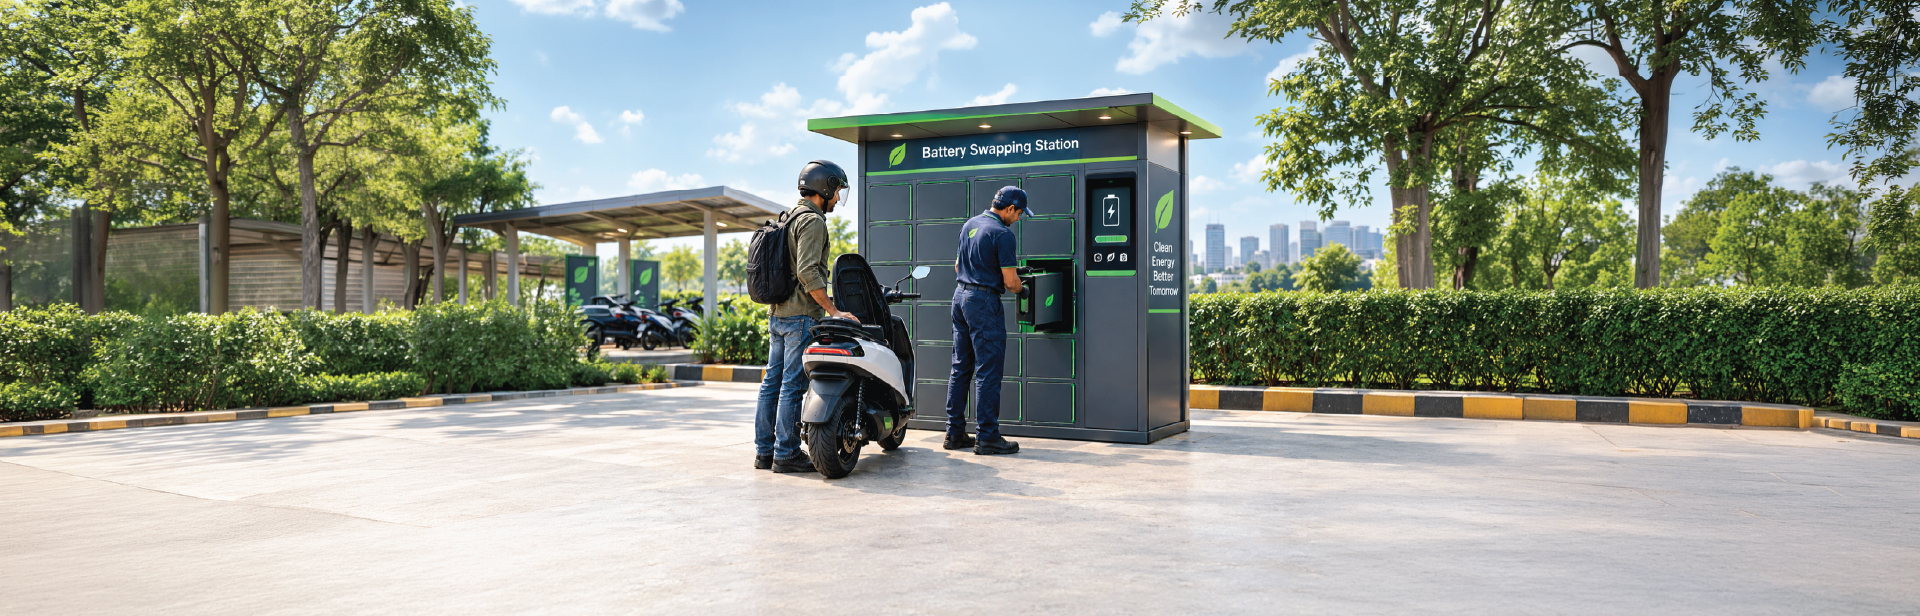
The cost of battery swapping decouples the initial purchase cost of an EV from its most expensive component: the battery pack. Though it generally accounts for 40% to 50% of total vehicle cost, many EV users end up paying extra for new batteries due to poor maintenance.
Luckily, India’s Draft Battery Swapping Policy has created an ecosystem where battery ownership has taken a better form. It has become a subscription-based operational expenditure that changes the loan underwriting and credit risk for EV lenders.
Financial institutions, fleet operators, and commercial drivers benefit from this shift as it reduces asset-level default risk. Even better, it optimizes how EV batteries are managed due to newer requirements for battery traceability and interoperability.
How Does Battery Swapping Restructure the EV Financing Risk?
Separating the vehicle chassis from the battery directly lowers the upfront capital requirement for buyers. What’s interesting is how it also cancels out the price depreciation risks of traditional vehicles. Here are the core risk impacts:
- Lower Initial Loan Exposure by 40%: Many green financiers underwrite only the vehicle chassis and motor. This automatically lowers the average loan principal in case of an electric three-wheeler (EV-3W) loan. We’re looking at a principal amount that drops from ₹3.5 lakhs to under ₹2 lakhs.
- Cancels Battery Degradation Risk: Battery capacity loss over 3-4 years takes away your green asset’s repossessable value. The catch is that the BaaS (Battery-as-a-Service) model puts the cell degradation risk and replacement costs on the battery service provider.
- Increases Borrower’s Cash Flow Stability: Commercial EV drivers save around 80% in downtime as compared to fixed-charging stops. This is because swaps take under 3-5 minutes. Notice how this increases their daily earning hours and improves the overall rate of monthly loan repayments. When you calculate the compounded value, it’s clear that the borrower ends up with a better cash flow.
Green loans with swappable batteries are ~50% lower. Moreover, the accuracy of the vehicle’s repossession value is more predictable since it isn’t fixed to an ageing battery.
Policy Framework and Regulatory Benefits in India
NITI Aayog’s policy framework standardized safety and tax structures to scale battery swapping networks across tier-1 and tier-2 Indian cities. For example, it aligns the 18% GST on standalone EV battery subscription services with the lower 5% GST charged on complete electric vehicles. This equalizes a consumer’s costs.
Secondly, there’s a mandate for unique identification numbers (UIN) and advanced battery management systems (BMS) for every swapped battery pack. This helps with a regular flow of real-time data on state of charge (SoC) and cell health.
There’s also a constant improvement in interoperability standards. The phased rollout of standardized connector designs and communication protocols is gradually allowing a single battery pack to operate across multiple vehicle OEMs.
Also Read: Battery Swapping vs Charging Stations: What’s More Bankable in 2025?
What Are Lenders Considering?
Credit assessment is moving from simple vehicle valuation to dual-party risk analysis. This is because the vehicle asset is split into two entities, namely the OEM and the energy operator. Here’s what green lenders for EVs factor in:
- Energy Operator Suitability: Assessing the uptime and network density of the BaaS provider that manages different battery swapping stations.
- Tri-party Agreements: Implementing legal contracts between the lender, fleet operator, and also the battery swapping provider. This lets relevant parties pause battery access in the event of sustained loan default.
- IoT Data Integration: Tracking telemetry data to verify daily mileage and battery swap cycles. This feature gives lenders early warning indicators of lower operational activity.
These steps are to secure the EV user’s investment and provide a quality of service that improves the vehicle’s lifespan. Get in touch with Ecofy to get a reliable green loan partner that tailors commercial loans and delivers rapid approvals. All in all, don’t forget to always inquire about the battery swapping policy to make your new EV fleet immune to avoidable costs.
FAQs
Who owns the battery in a Battery-as-a-Service (BaaS) financing model?
The battery is owned and maintained by the Energy/BaaS service provider, while the vehicle owner leases or pays per swap.
How do lenders protect their loan assets if the vehicle and battery are separated?
Lenders secure a primary lien on the vehicle chassis and utilize integrated GPS/BMS telemetry provided by the BaaS partner to monitor asset location and operational status.