
Financial Planning Tips for Your 20s, 30s, and 40s
- Published on Nov 11, 2026
- Read Time 7 mins
-
A lot of conventional financial advice follows the same repetitive ideas. Save a percentage of your salary. Invest in mutual funds. Buy life insurance. These foundational steps matter, but they also standardize financial planning and overlook another great avenue. The one where you can lower your lifestyle’s operating expenses and simultaneously stock up on assets that generate yields.
Remember, two pressures you can’t dodge are high utility inflation and changing tax structures. They force you to manage recurring liabilities as carefully as your investment yield.
We suggest that investing in sustainable asset upgrades is a great opportunity for this generation. From electric two-wheeler loans to locking in zero-cost power with rooftop solar loans, there’s a lot to save by optimizing your cash flow and reducing inflation stress.
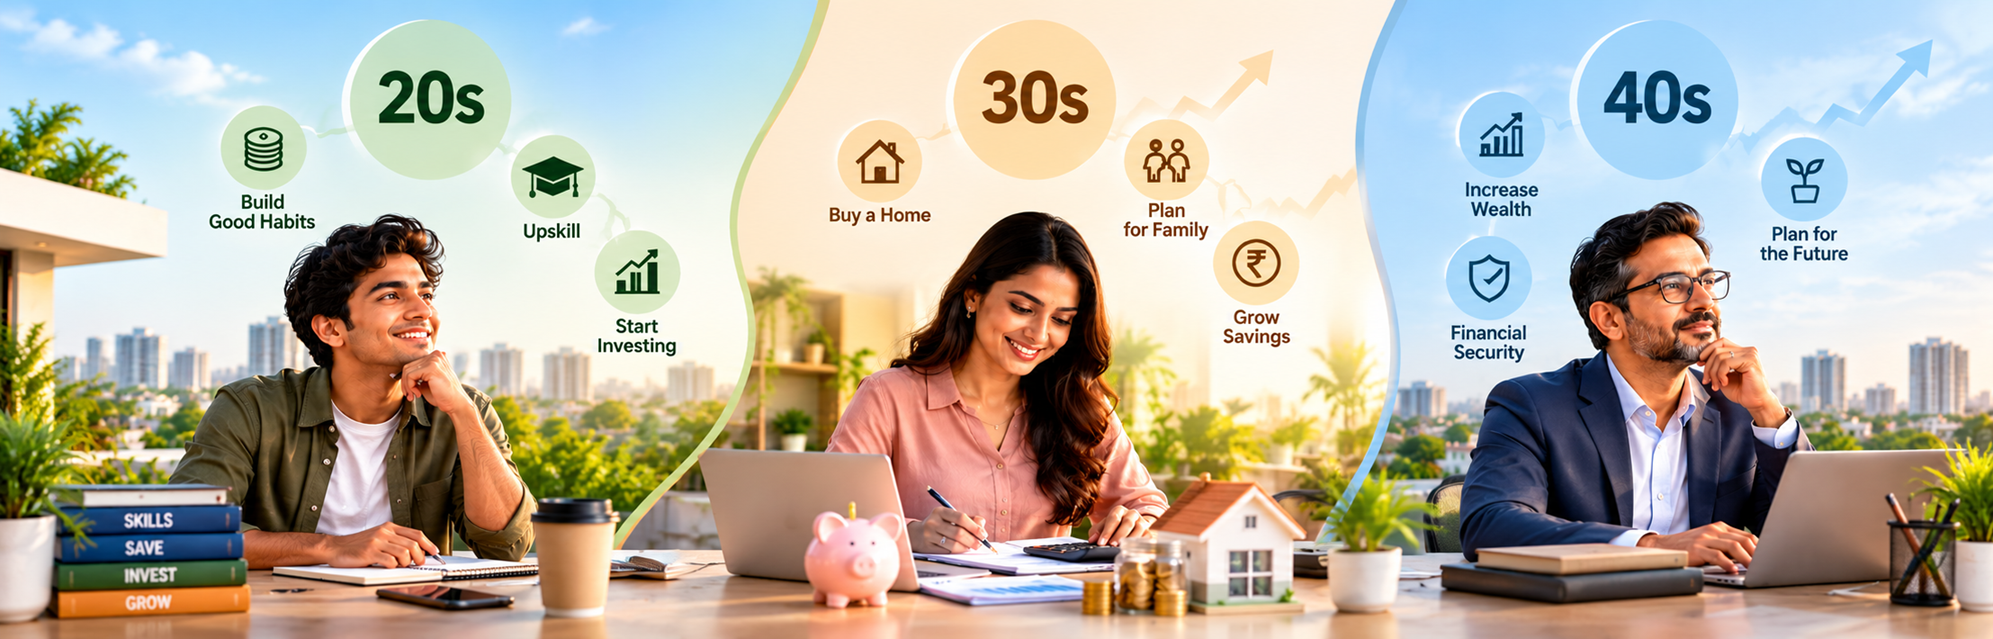
Setting the Base and Reducing Commute Leakage for Financial Planning in Your 20s
Your 20s require you to be mobile with career decisions and aim for long investment horizons. However, early income is often eaten away by high variable costs like rent or daily commuting expenses.
Start by prioritizing the financial basics: a 3-6 month emergency buffer, followed by high-equity mutual fund SIPs. This keeps a brief period of living expenses in liquid form via fixed deposits or high-yield savings accounts.
Spending ₹3,000-₹8,000 monthly on fuel for daily commute burns capital that’s better used in equity SIPs. Try moving to an EV-2W to bring your per-kilometre costs below ₹0.30.
Key Takeaways
Here’s The Deal: Compounding works best when you reduce fixed expense leakage early. Saving ₹3,500 every month on petrol in your 20s and redirecting that capital into a diversified equity SIP can compound into an additional ₹35+ Lakhs by the time you retire.
Also Read: What to Do if You’re Struggling to Repay Your Loan
Asset Creation and Home Energy Freedom for Financial Planning in Your 30s
The confusion in managing finances has probably increased in your 30s because of homeownership or marriage and parenting. Utility bills also surge as household power consumption grows with multiple air conditioners and home electronics. A 3kW or 5kW rooftop solar system can help offset rising annual electricity costs and turn a recurring expense into a predictable, fixed asset.
Secure a collateral-free solar rooftop loan to improve your money’s flexibility in your 30s. The per-month loan EMI is generally lower than the electricity bills the solar system will take care of.
Tax Optimization and Business Scaling for Financial Planning in Your 40s
40s tend to meet your peak earning power. Business owners and MSME operators, or even corporate decision-makers, try and be more free from income tax liabilities. Some ways to do this include asset purchases that act as tax shields and de-risking portfolios into yield assets.
For example, green energy sources let your business claim 40% accelerated depreciation under Section 32 of the Income Tax Act. Keep in mind, this is only valid for the first year of your green energy usage. Another suggestion is to replace diesel or CNG delivery fleets with EV-3Ws to drop your operating expenses by over half.
Most importantly, if you’re a business owner in your 40s, look to expand operational capacity using green SME loans. The collective financial savings of using renewable energy let your business compete on higher ground among other sustainable businesses.
Verdict
If you’re above 50, aim to preserve capital and generate passive yield. Retiring with high monthly utility and transportation expenses strains fixed-income pension or SWP (Systematic Withdrawal Plan) cash flows. A fully paid-off rooftop solar array and electric vehicle can keep essential daily living costs near zero.
All in all, look on energy-independent homes and sustainable, cash-flow-positive commercial assets to the next generation.
FAQs
How does installing rooftop solar in your 30s assist with long-term retirement planning?
Solar panels carry a warranted operational lifecycle of 25+ years. By eliminating your monthly electricity bill in your 30s, you lock in decades of free power and reduce the total corpus needed to fund your retirement lifestyle.
Is an EV loan better than paying upfront cash from your personal savings in your 20s?
Financing an electric two-wheeler through a high-LTV EV loan lets you keep your liquid savings for emergency funds or higher-yielding equity investments. The daily petrol savings from the EV comfortably cover the monthly loan EMI.
Also Read: Online Green Loan Applications: Do’s and Don’ts to Stay Safe